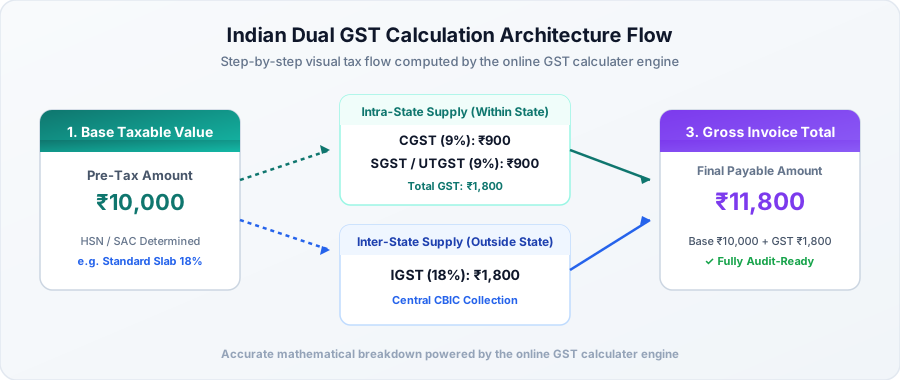
Latest GST Insights, Real Statistics & GST Calculator Case Studies
GST calculator data analysis, official tax revenue trends, and field case studies offer a candid look into how indirect taxation works on the ground across India. Drawing directly from monthly Ministry of Finance (PIB) press communiques, the GST Council, and real business audits, this portal unpacks where Indian businesses lose money to compliance gaps—and how they fix it. If you need to verify numbers for an upcoming invoice or return, try our main GST calculator tool.
₹20.18T
Annual Gross GST Collection
Official Ministry of Finance Data
1.46 Cr+
Active Registered Taxpayers
GSTN Portal Registered Base
89.4%
GSTR-3B Filing Compliance
Timely monthly return filing ratio
10.3 Cr+
Monthly E-Way Bills
National Inter-State Logistics Portal
Tax Knowledge Base: Research Articles & GST Calculator Guides
Explore our peer-reviewed indirect taxation guides, statutory analysis, and operational checklists designed to keep Indian enterprises 100% compliant.
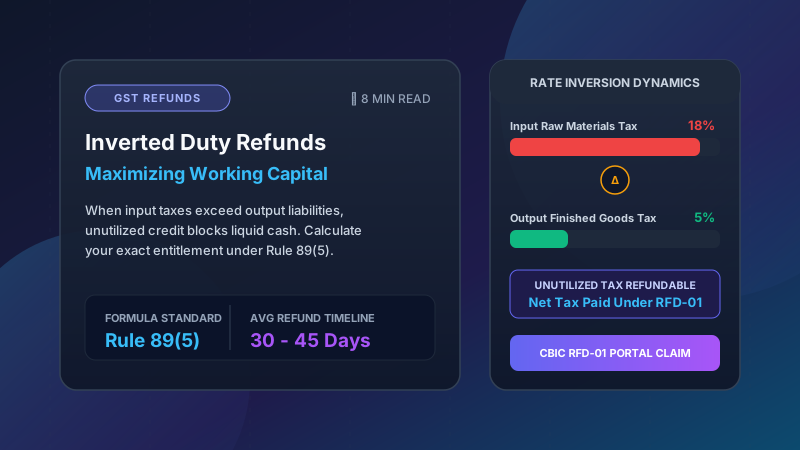
When raw material taxes exceed finished goods tax rates, valuable liquidity gets trapped. Learn how to calculate and claim statutory refunds under Rule 89(5) seamlessly.
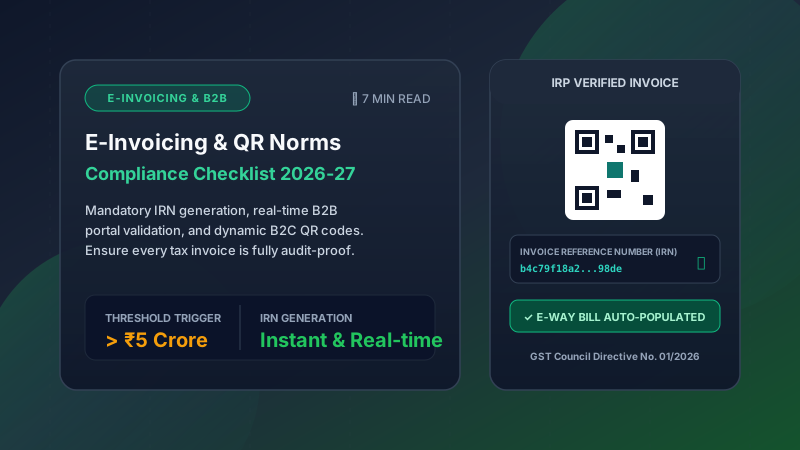
Mandatory real-time IRN generation, IRP validation, and dynamic B2C QR codes are essential for Indian enterprises. Review the latest statutory compliance guidelines.
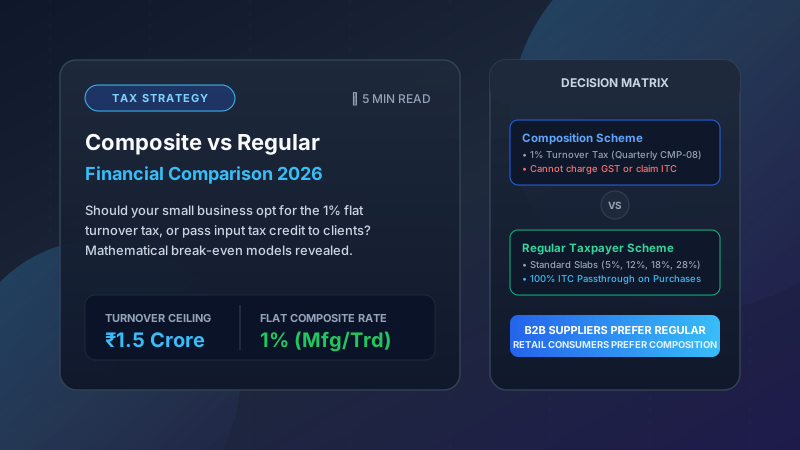
Evaluate the mathematical break-even point between opting for the 1% flat turnover tax versus standard multi-slab GST with full input tax credit passthrough.
Empirical Business Case Studies: GST Calculator in Practice
Tax compliance on paper looks simple, but real-world supply chains are full of messy vendor invoices, delayed filings, and unexpected departmental notices. These three real-world case studies illustrate how Indian businesses solved major cash traps and reconciled their records using systematic calculation frameworks:
Manufacturing MSME
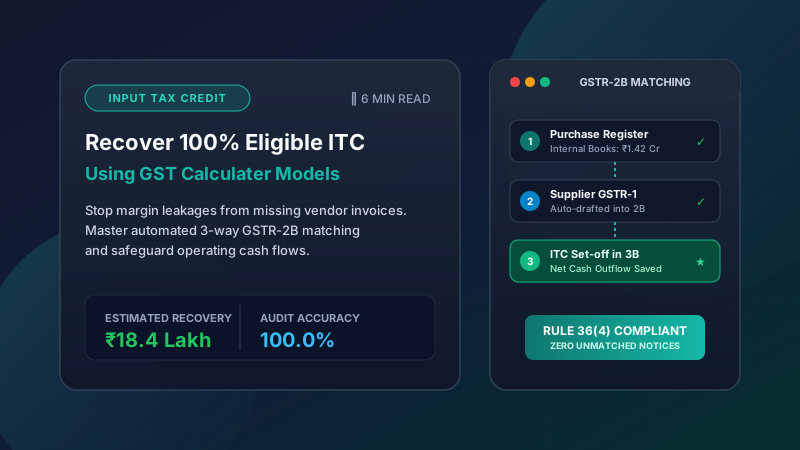
Case Study 1: Automotive MSME Recovers ₹18.4 Lakh Using GST Calculator
The case involves a Precision Gear Manufacturer based out of Pune who sourced alloy billets and tooling from Suppliers based out of Karnataka and Gujarat. Given the fact that the procurement team key-ed in the bills manually, the GSTR-1 filing by the Suppliers was delayed at times, over ₹21.6 Lakh of Input Tax Credit remained missing in the company's auto-drafted GSTR-2B. Without matching records, the finance team could not claim the credit in GSTR-3B. To keep operations moving, the business treated the uncredited tax as raw material cost, eroding net margins by 4.2% and squeezing cash reserves.
The GST Calculator Intervention:
The company brought in an external tax consultant who established a disciplined reconciliation protocol:
Mapped all incoming metal shipments to their exact 18% IGST schedules using standardized tax calculator models.
Ran automated monthly three-way reconciliations: Purchase Register vs. Vendor Invoices vs. GSTR-2B on the 14th of every month.
Updated supplier contracts so that 10% of invoice payments were withheld until the vendor's invoice appeared cleanly in GSTR-2B.
₹18.4 Lakh
Unclaimed ITC Recovered
14 Days
Working Capital Acceleration
0 Notices
Clean CBIC GSTR-9 Audit
B2B SaaS / IT Services
Case Study 2: SaaS Exporter Unlocks ₹42 Lakh via Zero-Rated LUT Workflow
Bengaluru, Karnataka
Industry: Cloud Software & IT Consulting (SAC 998313)Annual Turnover: ₹14.2 CroreFiling Status: 100% Export of Services
The Challenge:
A cloud software startup based in Bengaluru billed clients primarily in the US and Europe. Unaware of the practical nuances of export filings, their accounts team had been paying 18% IGST on every foreign invoice and subsequently filing manual refund claims (RFD-01). Because departmental scrutiny took 90 to 120 days for each refund batch, the startup had ₹42 Lakh of essential operating cash trapped inside the government treasury at any given moment.
The Solution:
Following our Dual GST Guide on export provisions, the company submitted an online Letter of Undertaking (LUT) under Rule 96A via the GST Portal before the start of the fiscal year. This allowed them to bill international clients at 0% tax liability without paying IGST upfront. Meanwhile, they continued to accumulate legitimate Input Tax Credit on domestic office rent, laptops, and server infrastructure, filing quarterly refund applications for unutilized ITC.
₹42 Lakh
Upfront Working Capital Saved
100% Zero-Rated
Export Invoicing Compliance
90+ Days
Eliminated Refund Wait Time
Logistics & Supply Chain
Case Study 3: Cold-Chain Logistics Resolves ₹9.2 Lakh RCM Discrepancy
A cold-chain freight company operating across Delhi, Haryana, and Uttar Pradesh received an audit notice from the State GST Department demanding ₹9.2 Lakh in unpaid tax, plus interest. The department claimed the transporter had failed to pay GST on freight charges. The transporter had assumed that their corporate clients had already discharged the tax under the 5% Reverse Charge Mechanism (RCM), but their consignment notes lacked the mandatory statutory declaration.
The Solution:
Using our GST Formulas and RCM compliance templates, the transporter's chartered accountant gathered certificates from all recipient registered companies confirming that 5% RCM liability had indeed been deposited via GSTR-3B under Section 9(3). The tax team also produced their online Annexure V declaration filed on the GST portal, proving the transporter had not opted for the 12% forward charge route.
₹9.2 Lakh
Notice Demand Dropped
₹0 Penalty
Complete Audit Clearance
100% Clear
Standard Consignment Bilty Updated
Official Indian GST Statistics (FY 2024-25 & 2025-26) - GST Calculator Analysis
Indirect tax receipts published monthly by the Press Information Bureau (PIB) and CBIC illustrate the rapid formalization of India's commercial economy:
Fiscal Year
Gross Annual GST Collection
Average Monthly Revenue
YoY Growth Rate
Active Taxpayer Base
FY 2025-26 (Projected/Current)
₹22.10+ Lakh Crore
₹1.84 - ₹2.10 Lakh Crore
+9.5%
1.46+ Crore
FY 2024-25
₹20.18 Lakh Crore
₹1.68 Lakh Crore
+11.7%
1.42 Crore
FY 2023-24
₹18.07 Lakh Crore
₹1.51 Lakh Crore
+12.1%
1.38 Crore
FY 2022-23
₹15.96 Lakh Crore
₹1.33 Lakh Crore
+21.8%
1.34 Crore
Why are tax collections consistently setting new records? Three administrative factors stand out:
E-Invoicing Rollout Down to ₹5 Crore Turnover: Businesses can no longer issue backdated paper invoices for B2B transactions; an Invoice Reference Number (IRN) must be generated in real-time from the Invoice Registration Portal.
Automated GSTR-1 vs. GSTR-3B Mismatch Notices (DRC-01B): If outward tax declared in GSTR-1 exceeds the tax paid in GSTR-3B by a predetermined threshold, the GST portal issues an automated notice requiring explanation or immediate payment before the next return can be filed.
Radio-Frequency Identification (RFID) & E-Way Bill Integration: Toll plazas and commercial check-posts cross-verify digital e-way bills automatically as trucks transit interstate highways, drastically reducing unaccounted transit.
⚖️
Editorial Policy & Government Data Verification
All statistical figures, fiscal milestones, and case studies published on this portal are fact-checked against official releases from the Ministry of Finance (PIB New Delhi), the Goods and Services Tax Network (GSTN), and CBIC circulars. Mathematical calculations are cross-verified using our standardized indirect tax formulas.
Ensure 100% Tax Accuracy with our GST Calculator
Prevent costly credit mismatches and audit notices by calculating your exact GST figures in seconds.
 Input Tax Credit
⏱ 6 min read
 GST Refunds
⏱ 8 min read
 GST Invoicing
⏱ 7 min read
 Tax Strategy
⏱ 5 min read